
What It Really Takes to Sell a Business, and Why Most Owners Underestimate It
Updated: 2 days ago
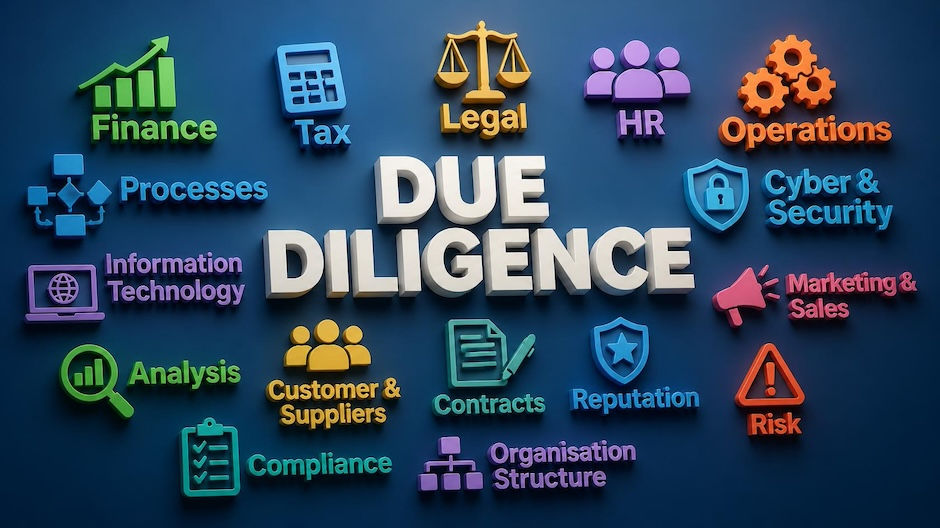
In June 2023, I completed the sale of my managed services business. From the first serious conversation to the final signature: fifteen months. Everything in this series is written for people about to do the same, MSP (Managed Services Provider) owners thinking about their own exit.
Ask most business owners how long a sale takes, and they'll talk about finding a buyer and agreeing a price. That part, in my experience, was almost the easy bit. The part nobody warns you about is what comes next: hundreds of detailed questions, from solicitors, accountants, HR specialists and the buyer's own technology team, covering every corner of the business.
All of that happens while you're still running the business, day to day. Selling isn't a task you get to put everything else down for. The demands of due diligence land on top of your normal workload, and for most owners, juggling both, not any single question a buyer asks, is the real challenge.
By completion, those questions had touched nine distinct areas: Finance, Tax, Legal, HR, Operations, Processes, Cyber & Security, Information Technology, and Marketing & Sales. Some were straightforward. Most weren't. Answering them properly, not just quickly, but with evidence, context and consistency, is what actually decides whether a deal completes smoothly, drags on for months, or falls apart.
Here's the bit most owners get wrong: they assume their accountant has this covered. For finance and tax, that's often true. For the other seven areas, it usually isn't. IT, cyber security and the detail of customer and supplier relationships are almost never within an accountant's remit, and they're consistently where deals slow down.
There's another imbalance worth naming up front. Most owners sell a business once, maybe twice, in a lifetime. The buyer's side, and often their own advisers, may have done this many times over. That gap alone can put a seller at a disadvantage before the first real question is even asked, unless they go in already knowing what's coming.
The good news: none of this is actually hard, if you start early and know what to expect. Nearly everything a buyer asks for already exists somewhere in your business, in a filing cabinet, a shared drive, or someone's head. The work isn't creating information from nothing. It's finding it, organising it, and having it ready before anyone asks.
Over the next nine posts, I'll walk through each of those nine areas: what a buyer typically wants to see, why it matters, and what it actually takes to get ready, while still keeping the business running. My aim isn't to make selling a business sound daunting, it's the opposite. Once you can see the shape of the work, it stops being overwhelming and starts being a checklist you can work through alongside everything else you're already doing.
If you're even vaguely thinking about an exit in the next couple of years, it's worth reading all nine. Knowing what's coming is most of the battle.
If this has you wondering how ready your own business is, the free readiness assessment will show you where to look first, in about three minutes.
Comments